How to Navigate an Insurance Claim
Dana Whitfield
Claims Advisor
JUL 28, 2026
6 min read
A roof claim is won or lost in the first week. Insurers cover sudden storm damage, not gradual wear, so the sooner you file and the better you document, the simpler the whole process becomes.
1. Photograph Everything Before You Clean Up
Start wide to establish the property and date, then move in close on each damage point. Capture fallen branches, dented gutters, granules washed into the driveway, and any interior staining. Tarp what needs tarping, but leave permanent repairs until the adjuster has been.
Reasonable emergency repairs are usually reimbursable, so keep every receipt for tarps, fans, and labour.
2. Know What Your Policy Actually Pays
Two lines in your policy decide the size of your cheque. Find them before you make the call, not after the offer arrives.
- Your deductible, which may be a percentage for wind and hail
- Whether you hold actual cash value or replacement cost coverage
- Any age limits applied to the roof surface
- The reporting deadline after a loss event
3. Bring Your Own Inspection to the Table
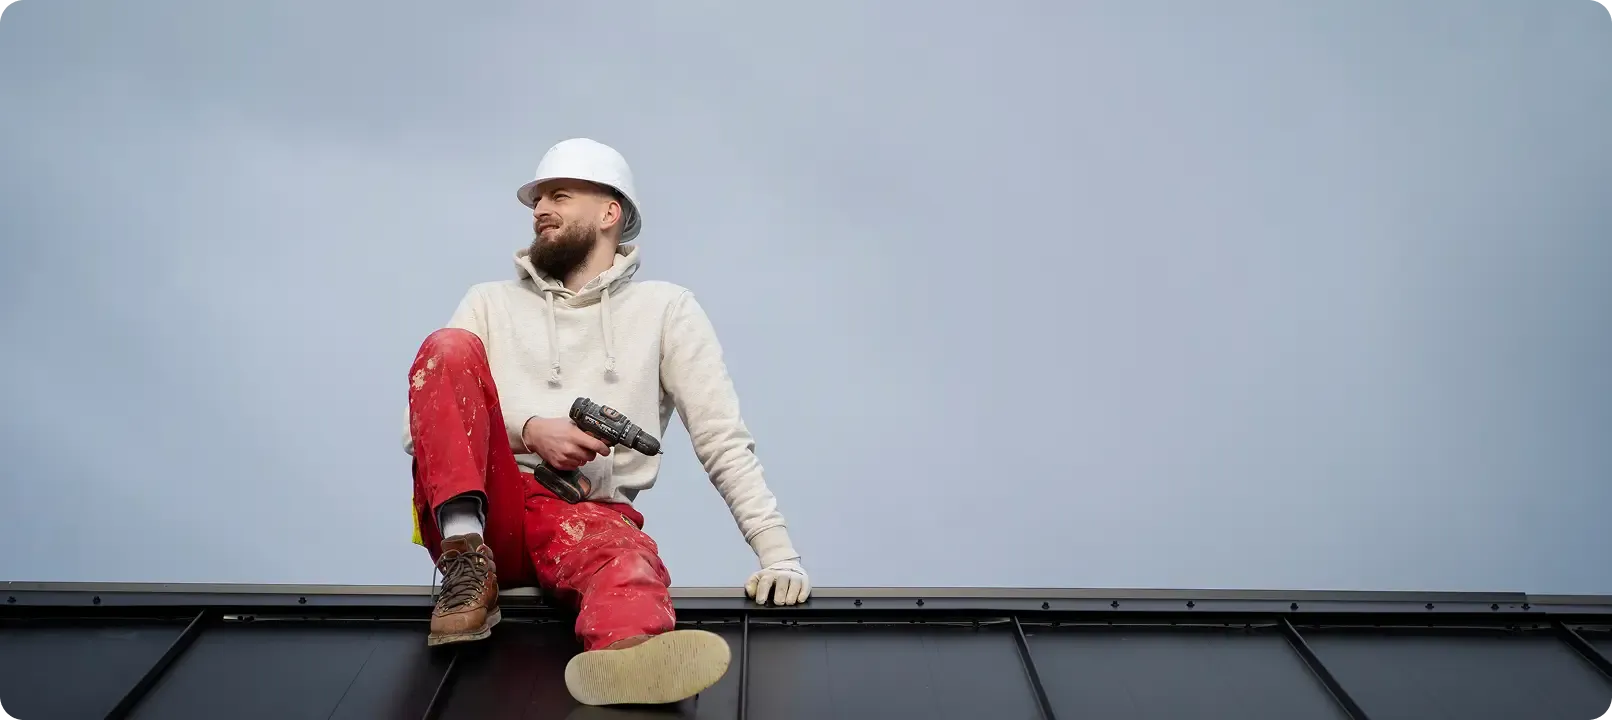
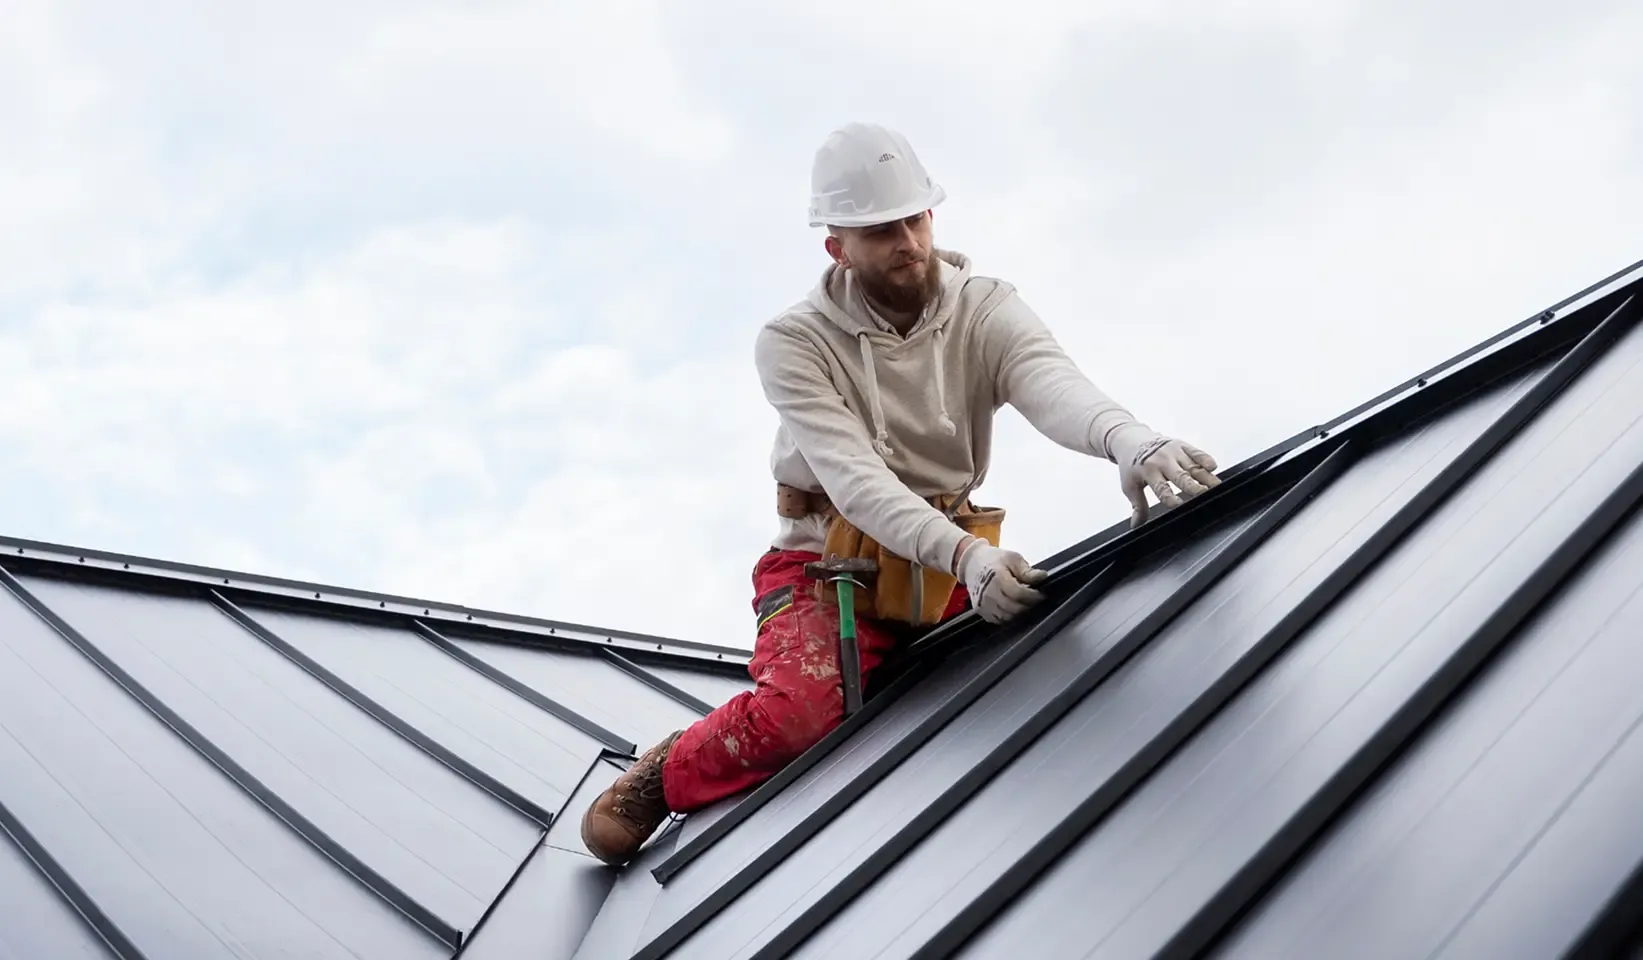
Have a licensed roofer document the damage before the adjuster visits, then be present for the walkthrough. When items like underlayment, drip edge, or code upgrades are missing from the estimate, your contractor can file a supplement with photographs to support it. That is routine, not a fight.
10 years handling storm damage claims for homeowners across the region. Licensed public adjuster.
Leaks rarely begin where the stain appears. Here is where to actually look.
A step-by-step guide to getting storm damage covered without the headache.
Asphalt, metal, or tile? Compare lifespan, cost, and curb appeal side by side.